
For the future
Our Five Material Issues
The core of our sustainability management strategy is to set targets for each priority theme identified through our materiality assessment (key issues) and promote initiatives to achieve those targets. To reflect the changing external environment, we regularly review our materiality and priority themes and revise them as necessary. Following a review, we updated some of the priority themes in June 2026 and are currently pursuing initiatives based on five material issues and 12 priority themes. We aim to mitigate business risks while identifying opportunities for innovation by prioritizing the allocation of internal resources to these themes, thereby achieving medium- to long-term growth.
Priority Themes and Major Measures Based on Materiality

Materiality identification / review process
Internally review KPI progress
We conduct interviews with each of the subcommittees involved in the re-identification of materiality. We compile a range of key issues, views and ideas from the subcommittee members, including general managers and staff members charged with tasks, and collate data based on various themes.
Analyze external evaluations
We monitor changes in the external environment that may affect sustainability by reviewing relevant literature and keeping up to date with the latest developments. We then consider how these changes may affect the food industry, check our findings against the data collected in Step 1, and identify social issues that are highly relevant to the Calbee Group.
Review the Materiality Map
In order to review the Materiality Map, we took into consideration the results of the analysis of external evaluations conducted in Step 2, and re-evaluated each of the social issues identified based on their importance to stakeholders and to Calbee, as indicated on the vertical and horizontal axes, respectively.
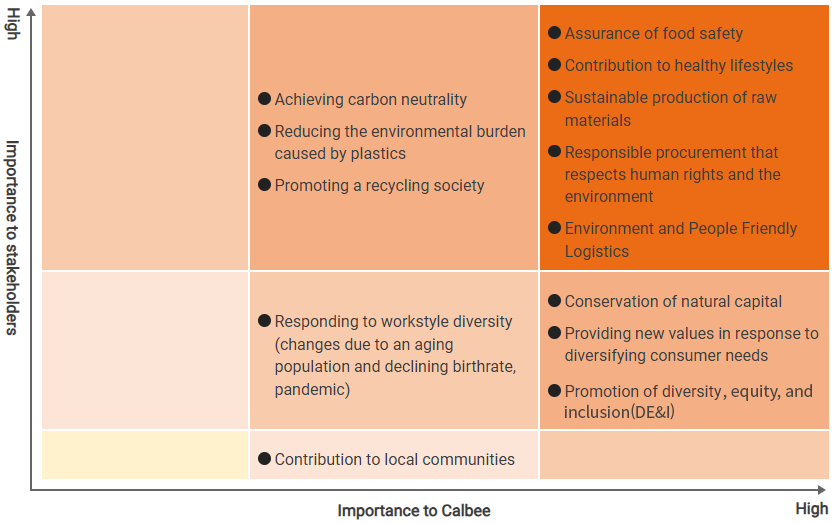
* The Materiality Map is current as of June 2026.
Review materiality
We regularly review and update our materiality to reflect changes in the external environment. We review the social issues on the map and examine how our materiality relates to changes in the external environment.
Review and finally identify measures and KPIs
We discuss key measures related to our material issues and draft KPIs with the subcommittees we consult and with relevant departments. We also seek feedback and advice from external experts on the review process and the proposed materiality to confirm that both are appropriate.
The proposed materiality and draft KPIs receive final approval at a meeting of the Sustainability Committee, after which we adopt the approved issues as our new materiality and begin addressing them.
At the 7th meeting of the Sustainability Committee in December 2022, we identified five new material issues and 13 priority themes. Following further reviews, we consolidated these priority themes into 12 at the 14th meeting of the Sustainability Committee in June 2026.
Review of the appropriateness of materiality by conducting interviews with external experts
We interviewed two experts to verify the re-identification of materiality from external perspectives.
We took their views into consideration when we re-identified materiality.
Japan Director, CSR Asia Ltd.
Ms. Makiko Akabane, who has abundant knowledge of CSR and the sustainability initiatives of both Japanese and foreign companies, gave us feedback and advice to help us practice globally applicable sustainability management.
We conducted interviews in October 2022, when we reassessed our materiality, and again in October 2026, when we introduced additional priority themes.
Comments from October 2022
-
●Food manufacturers with overseas operations are expected to give consideration to small farmers in the ingredient procurement process, guarantee wages for their factory workers, and deal with the issue of plastic packaging materials. They are under intense public scrutiny.
-
●Foreign companies seem to be more interested in setting ambitious targets than in disclosing their KPIs. Many of them write mission statements like: "This is the kind of company we are and this is the kind of society we want to create. That’s why we are doing this." The difference between Japanese companies and foreign companies is that the latter tend not to focus on KPIs or the PDCA cycle, as is common practice in Japan. When you disclose information and communicate with audiences on English language media, you should pay careful attention to how to express yourself in the English language.
-
●Animal welfare will be an increasingly important concern. You are not required to include animal welfare among your material issues when you disclose materiality, but nevertheless, it would be better if you could mention that you have started internal discussions on animal welfare when you disclose your review process.
Comments from October 2026
-
●In recent years, the concept of DEIB (Diversity, Equity, Inclusion & Belonging) has gained increasing attention in the field of human capital management. In particular, "Belonging" refers to a state in which individuals feel accepted, have a sense of belonging, and are able to thrive. I believe Calbee’s "Active Roles for All Employees" initiative aligns closely with this concept.
-
●Calbee’s ability to view global challenges through a worldview rooted in potatoes is a distinctive strength. Communicating this perspective through its disclosures will help differentiate Calbee from its peers and more clearly convey what makes the company unique.
Professor, Rikkyo University
Professor Kawaguchi, who has a high level of expertise in all aspects of sustainability, gave us feedback and advice on changes in the external environment that have an impact on the Calbee Group and stakeholders’ expectations.
We conducted interviews in October 2022, when we reassessed our materiality, and again in October 2026, when we introduced additional priority themes.
Comments from October 2022
-
●There is a high level of need for plastic alternatives in our society today, and people may have the impression that the Calbee Group is not doing enough compared to other leading food manufacturers. I think you should clearly indicate your efforts to reduce plastic use as one of your material issues and priority themes.
-
●Here’s what you could do: place your efforts to protect natural capital at the beginning of your narrative when you mention the relationship between sustainable agricultural production, which is an ongoing material issue, and the protection of natural capital, which is a new theme. Highlight keywords, such as "nature’s gifts," which are part of the corporate philosophy that you embrace and follow. And write a story about Calbee’s co-creation with farmers even if you cannot make Calbee the subject of a sentence. I think these things are important.
-
●Animal welfare is an issue that you should be prepared to address, although you do not need to categorize it under the materiality heading. Animal welfare, egg production in particular, is likely to come under scrutiny.
Comments from October 2026
-
●With regard to the newly established priority theme, "Maximization of human capital toward realizing Active Roles for All Employees" maximizing human capital should not be viewed as an end in itself. It is important to communicate, both internally and externally, how this capital can be leveraged to generate financial and non-financial returns for the company, while also enabling employees themselves to find purpose, satisfaction, and a sense of fulfillment in their work. "Enabling every employee to thrive" is an effective expression of the principle of inclusion. It is therefore essential to put in place mechanisms and systems that create an environment in which everyone can contribute and succeed.
-
●Many ESG investors have already begun to focus on food companies as a sector with significant exposure to, and dependence on, natural capital. Given Calbee’s reliance on raw materials such as potatoes, it appears necessary to place even greater emphasis on conserving—and ultimately enhancing—natural capital as a management and financial risk consideration.
Materiality review history
To reflect the changing external environment, we regularly review our materiality, priority themes, and KPIs and revise them as necessary.
-
●May 2020Materiality identification
Eight material issues and their priority themes were identified. -
●December 2022Materiality review
Five material issues and 13 priority themes were redefined.
The reasons behind the review included the COVID-19 pandemic, emerging human rights issues, and the growing importance of natural capital. -
●December 2023KPI revision (Priority theme: Providing new values in response to diversifying consumer needs)
As the original target was set for the fiscal year ended March 2024, a new annual target was set. -
●June 2025KPI revision (Priority theme: Promoting a recycling society)
As the food loss target was set for the fiscal year ended March 2024, a new target was established for the fiscal year ending March 2031. -
●December 2025KPI revision (Priority theme: Achieving carbon neutrality)
Targets for each Scope category were set. -
●June 2026KPI revision (Priority theme: Promoting a recycling society)
Metrics used to measure reductions in water consumption and waste generation were changed from total volume to per-unit intensity.
Priority theme and KPI revision (Materiality: Promote Active Roles for All Employees based on diversity)
The priority theme was revised to "Maximization of human capital to realize Active Roles for All Employees" to encompass a broader range of issues, including those covered by the previous priority themes, "Responding to diverse workstyles" and "Promotion of diversity, equity, and inclusion."